Many shoppers focus on the advertised price or monthly payment. However, neither number necessarily tells you how much you must pay to complete the purchase.
The Federal Trade Commission recommends obtaining the full out-the-door price in writing before visiting a dealership. This can help buyers compare vehicles, identify unexpected charges, and avoid negotiating solely around monthly payments.
Understanding the final purchase price also makes it easier to determine how much financing you actually need.
This guide explains what belongs in a typical out-the-door quote, how optional add-ons work, and what to review before signing a contract.
Used Car Out-the-Door Price: What Should Be Included?
The out-the-door price is generally the amount required to complete the vehicle purchase before accounting for financing interest paid over time.
It typically includes the vehicle’s negotiated selling price together with applicable taxes and fees.
However, individual charges and legal requirements vary by state.
Understand the Difference Between Sticker Price and Final Price
The amount shown in a vehicle advertisement is a useful starting point, but it may not represent the final transaction total.
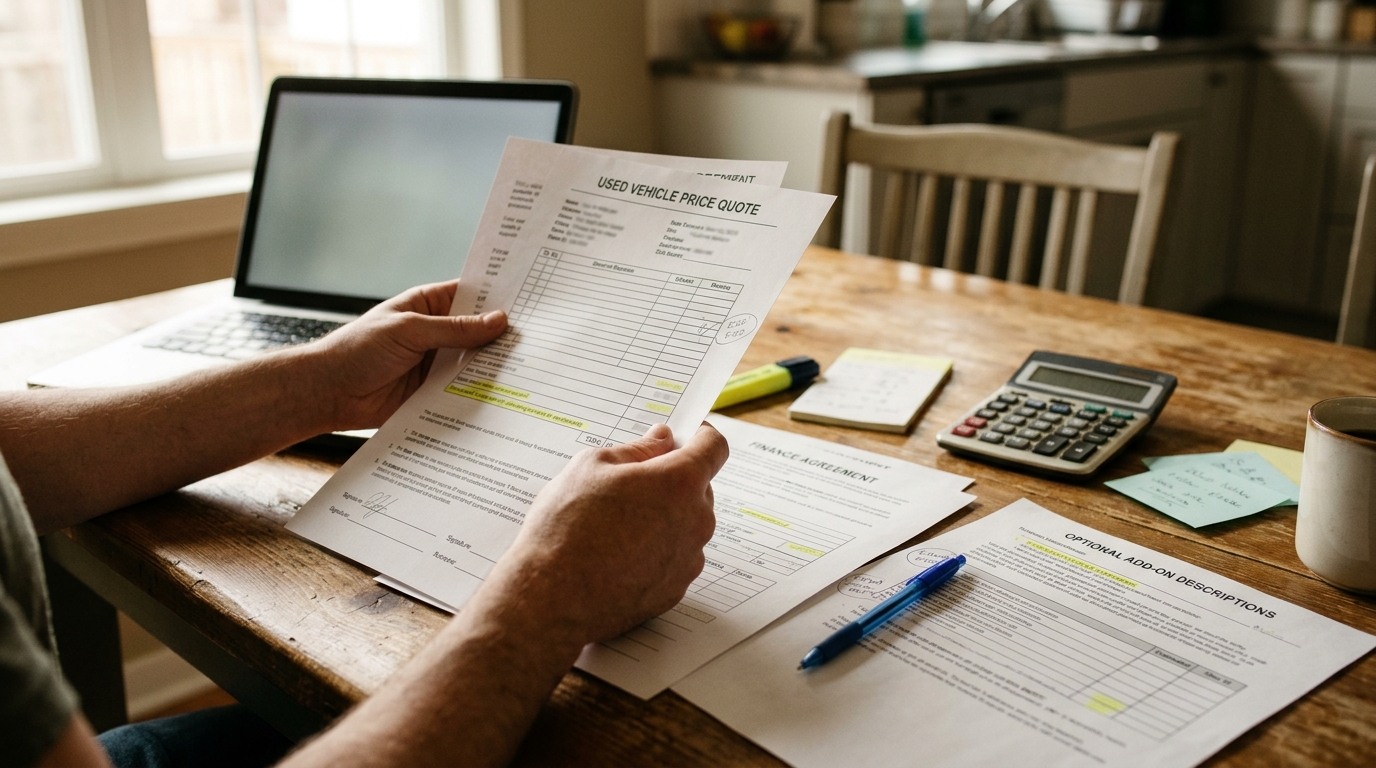
Buyers should request an itemized written estimate that identifies each charge.
Vehicle Price, Taxes, Registration, and Documentation Charges
A typical used-car purchase may include the negotiated vehicle price, sales tax, title charges, and registration fees.
Some dealerships also charge documentation or processing fees.
The permitted amounts and disclosure requirements depend on state law and the circumstances of the sale.
For example, a documentation fee may be subject to a state limit in one jurisdiction but handled differently in another.
Therefore, buyers should avoid assuming every dealership must charge the same fees.
Instead, ask which charges are legally required and which are imposed by the seller.
Request a complete breakdown before travelling to the lot.
The FTC recommends comparing written out-the-door quotes from different dealers.
That approach makes it easier to evaluate the overall deal rather than becoming distracted by a low advertised figure.
For authoritative guidance, review the FTC’s used-car purchasing guide.
Why the Lowest Advertised Price May Not Be the Best Deal
Imagine two dealerships advertising similar used vehicles.
The first lists a vehicle for $17,500, while the second asks $18,000.
At first glance, the cheaper listing appears better.
However, suppose the first dealership includes additional charges for optional products that raise the final price substantially.
The second dealership may ultimately offer the lower out-the-door total.
This example is illustrative rather than a statement about any particular seller.
The central lesson is to compare the total price for vehicles with similar equipment and condition.
A comparison should also account for mileage, warranty terms, repair history, and other differences.
A car that costs slightly less at purchase could require significantly more maintenance afterward.
Therefore, the lowest transaction price is not automatically the lowest total ownership cost.
Use the out-the-door figure alongside a vehicle inspection and realistic budget.
Dealer Add-Ons That Can Increase the Final Price
Dealerships sometimes offer optional products alongside the vehicle itself.
These may provide value for certain buyers, but their costs should be clearly understood.
Service Contracts, GAP Products, and Protection Packages
Common dealer add-ons include vehicle service contracts, GAP coverage, VIN etching, rustproofing, and paint or fabric protection.
A vehicle service contract may pay for certain future repairs under specified conditions.
However, it is not identical to a manufacturer’s original warranty.
Coverage can contain exclusions, deductibles, waiting periods, and cancellation provisions.
GAP products generally relate to certain differences between a vehicle’s loan balance and an insurance payment after a qualifying total loss.
However, terms vary, and the product may not cover every remaining loan-related expense.
Buyers should compare the cost and benefits with alternatives from other providers.
Some options may not be needed at all.
According to the FTC, consumers should understand and approve optional add-ons rather than discovering them unexpectedly in the final contract.
How to Recognize Unwanted or Unexplained Charges
A line item with an unfamiliar description deserves an explanation.
Ask what the product or service provides, whether it is optional, and how much it costs.
Do not assume a charge is mandatory merely because it appears on a printed form.
Likewise, a salesperson’s statement that every buyer purchases a particular product does not prove it is legally required.
The FTC has warned about deceptive practices involving add-ons that buyers did not knowingly authorize.
However, buyers should not assume every dealer charge is unlawful.
Some fees may be legitimate and required under applicable rules.
The goal is to distinguish authorized charges from unnecessary or misrepresented products.
Obtain the explanation in writing whenever possible.
Read the FTC consumer alert on unwanted dealer add-ons for further background.
How to Negotiate a Used Car Out-the-Door Price in 2026
A clear negotiation begins before the buyer arrives at a dealership.
Researching comparable vehicles, checking financing options, and obtaining written estimates can reduce uncertainty.
Compare Quotes, Review Financing, and Inspect the Final Contract
Focus on the total purchase amount rather than accepting an attractive monthly payment without understanding the complete agreement.
Request an itemized quote before visiting.
Contact several dealers about vehicles that meet your needs.
Ask each seller to identify the vehicle, its price, taxes, fees, and optional products.
Confirm whether advertised discounts have eligibility requirements.
Also ask whether the specific vehicle remains available.
Save the written response so that you can compare it with the final contract.
Separate vehicle negotiation from financing.
Financing decisions affect the total cost of borrowing.
A low monthly payment can result from extending the loan term, which may increase interest paid over time.
Therefore, compare the annual percentage rate, loan length, amount financed, and total finance charge.
Obtaining a financing offer from a bank or credit union before visiting the dealership can provide a useful comparison.
However, lenders use different approval criteria, and advertised rates may not be available to every borrower.
Our Presta Cars financing articles discuss budgeting and loan-related risks in more detail.
Check whether dealer add-ons are actually useful.
Before accepting an optional product, ask which risks it covers and what exclusions apply.
Compare its price with the likely benefit and any overlapping insurance or warranty protection.
For example, a service contract may duplicate existing factory warranty coverage for some components.
However, other contracts may provide different protection.
Read the full agreement rather than relying on a short verbal description.
Ask for a pre-purchase vehicle inspection.
A favorable out-the-door quote cannot compensate for a car with serious undisclosed mechanical problems.
Arrange an independent inspection when possible.
The FTC recommends this step even when a dealer says it inspected or certified the vehicle.
The mechanic can identify current problems and prepare a written estimate of necessary repairs.
That information may support further negotiation or a decision to buy a different vehicle.
Read the Buyers Guide.
Under the FTC’s Used Car Rule, covered dealers generally must display a Buyers Guide on used vehicles offered for sale.
The document provides important information about warranty status and buyer protections.
It should indicate whether the vehicle is being offered with specified dealer warranty coverage or under an as-is arrangement where permitted.
However, state laws may provide additional rights.
The Buyers Guide should be reviewed alongside the sales contract and warranty documents.
Do not rely solely on verbal assurances about repairs or returns.
Compare the final contract with the written quote.
Before signing, review every financial line item.
Confirm the vehicle identification number, selling price, taxes, fees, down payment, trade-in information, and any additional products.
If the contract includes an unfamiliar charge, request an explanation before proceeding.
Electronic signing does not remove the importance of reading the complete agreement.
Ask for a copy you can review clearly rather than signing on a small screen without seeing the terms.
Do not assume there is a universal three-day return period.
Federal law does not generally provide an automatic three-day cancellation right for every dealership vehicle purchase.
Some states have different rules or optional return arrangements.
Therefore, confirm the actual return policy before signing.
If a dealer promises a return option, request the terms in writing.
Do not rely on the assumption that the car can be returned simply because you change your mind.
Understand the total cost of ownership.
The out-the-door price is an important measure of the initial purchase cost.
However, it does not include every future ownership expense.
Fuel, electricity, maintenance, insurance, repairs, parking, and financing interest can substantially affect affordability.
Vehicle age and mileage also influence future repair risk.
Before buying, calculate a realistic monthly and annual ownership budget.
This makes it easier to choose a vehicle that remains affordable after the excitement of the purchase.
What to do if a dealer changes the quoted price.
Ask why the amount differs and request an updated written breakdown.
Possible explanations include changed taxes, optional products, financing conditions, or an error in the original quote.
However, some explanations may not be acceptable under applicable consumer protection rules.
Do not sign until the charges are clear.
If you suspect deceptive conduct, you can consult state consumer protection resources or report concerns through the FTC’s ReportFraud portal.
Frequently asked questions
What is a used car out-the-door price?
It is the total amount generally required to complete the vehicle purchase, including the negotiated price and applicable taxes and fees, before future financing interest.
Are dealer add-ons always required?
No. Many add-ons are optional, although applicable contract and legal requirements should be reviewed.
Can I negotiate the out-the-door price?
Buyers can request and compare written quotes and negotiate permissible elements of the transaction.
Is the monthly payment the same as the vehicle price?
No. Monthly payments depend on financing terms and may conceal a higher overall borrowing cost.
Does federal law guarantee three days to return a used car?
No. Return rights depend on applicable state law and any written dealer policy.
Final thoughts
Understanding a used car out-the-door price helps buyers recognize the actual transaction cost before committing to a purchase.
Written quotes, careful add-on reviews, independent inspections, and complete contract checks can reduce expensive surprises.
Compare the total cost rather than negotiating only the advertised price or monthly payment.
For more practical vehicle shopping information, visit the Presta Cars car buying tips section.
Editorial note: This article is based on U.S. consumer guidance available in October 2026. Dealer fee rules, taxes, and return policies vary by state.